Blog

  • Online Correspondence of Tax Notice: Real-time coordination with the Tax body:

    Online Correspondence of Tax Notice: Real-time coordination with the Tax body:

    You surely may have been tired while receiving the tax notices, preparing its reply manually, and submitting it while visiting the concerned tax office.

    So, your worrisome query has been eased by the FBR. Find out below how?

    There is a new update regarding the IRIS portal of the FBR; we will discuss it in this blog, its purpose, and what benefits it will have for the taxpayers in the future.

    Log in to the IRIS Portal and click on the MIS tab; a new page will open afterward. Multiple tabs will be there on the new page like foreign assets, fcy domestic, domestic assets, e-hearing, payment details, and action plan execution.    

    You have to know about the purpose of action plan execution, as it is the new addition. So let’s dig into this. If you click on action plan execution, you will see different new tabs: risk category, deficiency description, action plan, parent action plan, due date, actual date, status, and action.

    Now, why do these additions exist? What is their purpose? Will you receive the orders online? Will you communicate online with the FBR? And can you see your status anytime? 

    Let’s discuss its central idea, exploring the 4-5 key factors and the motive behind the development of a new update for which; why the FBR introduced the action plan execution.   

    Reduce the paperwork:

    What was happening before this? If ever you received any order from the FBR and often still you may also be receiving an order. So now you would eventually receive a message on your IRIS inbox or an email that reads ‘you have been selected for your audit, and you have to do correspondence of it, and that is its due date’ whatever it could be.

    Further you could also receive the message manually in the form of a letter through a courier or post office. In the letter, it is mentioned that a notice has been issued in your name. After that, you need to reply to this notice; after replying to it in the form of preparing the message manually, you have to submit it to the concerned office within the due date.

    This wastes the taxpayer’s time, commute expenses incurred by the taxpayer, and a burden of paperwork on the FBR. So, according to the new update in the portal, you will reply to the notice in the IRIS. The information and update of the notice will be displayed in the place execution tab, including its date, history, and scanned documents.

    This process will reduce the load on both sides, and the paperwork burden will end. All the communication and coordination will be conducted online.        

    Increase Efficiency:

    Suppose you have the due date of today at 12:00 AM and the official closing time of the office premises is 5:00 PM, so you can’t send the reply because the office gets closed after this time.

    But while online, when you have extended due date and time, you can submit it online at anytime, so it will be considered on-time response submission.

    So, this will lead to the increase in efficiency of the department, which will benefit you (the taxpayer) in return.

    Online Communication:

    FBR has learned from others during the covid about transforming the physical working environment into online working.

    The departments within and the officials are getting used to harnessing the online communication medium to save time and make communication meaningful, bookkeeping the record online on both ends.     

    Identification of Risk:

    This is the most important among all. Suppose you received any notice on the clause of income tax or sales tax, whichever section, so its risk category is already defined in the FBR internal policy, like which notice is on high risk and what risks are in which category.

    Accordingly, the departmental employees are got trained. Suppose there is a high-risk notice in the A category, so a special team or departmental wing of the FBR will entertain it.

    This makes the data coordination more analyzed from both ends.           

    Inter-Department Association:

    Suppose you communicate with a department within the tax, and commissioner appeal has passed the order, and you claim it Bonafede (no genuine order passed). So, you went to appeal it to the commissioner appeal. And you visited the second court for lodging an appeal. During the appeal, the concerned parties are presented; one is the department officer, and the other is the tax representative, who is you.

    There a discussion to be started, you have your arguments, and they have them. Communication means in the internal department, which is the commissioner appeal and the concerned department officer, so there is a lot of gaps between them. Often the commissioner appeal decides to be biased or unbiased.

    There are a lot of documents to be put on record in which how many orders are there in which the department charged the tax in the initial stage, but the commissioner appeal waived it off or how many orders are there in which the department charged the tax and even the commissioner appeal didn’t accept it. And also, how many orders are there in which the department charged the tax, and then the commissioner appeal agrees on 30-50% of the order. No proper documentation and record-keeping are available to the department currently. These steps are being taken into consideration to smoothen, streamline and automate the internal system.

  • Exemptions and Tax Concession: How to Legitimately Remain Safe by Paying in Less or No Taxes

    Exemptions and Tax Concession: How to Legitimately Remain Safe by Paying in Less or No Taxes

    There are some special exemptions and concessions in the second schedule; we will see what they are and how they will influence you.

    Subsection 1 of section 53, the income or classes of income, or persons or classes of persons specified are enlisted in the Second Schedule and have some special rates, tax exemption or concession from tax.

    What kind of relief could be, we are going to discuss them ahead, they shall be of: 

    (a) (exempt from tax under this Ordinance, subject to any conditions and the extent specified therein.)

    You could be given a tax exemption, but how you will be exempted is supported by some specific conditions mentioned in the second schedule. Furthermore, at what level you can be tax exempted? At this stage, you are required to be declared; tax exempted.

    (b) (subject to tax under this Ordinance at such rates, which are less than the rates specified in the First Schedule, as are specified therein;)

    Now in the first schedule, there is tax to rate clauses, in which you can choose according to those tax clauses. The tax rates that are available in the first schedule; which taxes have whatever rates? You will be taxed on those rates which are up to to your requirements.    

    (c) (allowed a reduction in tax liability under this Ordinance, subject to any conditions and the extent specified therein; or.)

    Your tax liability, which is calculated, can be reduced. Many examples are there whether you are a scientist, full-time researcher, specific teacher, etc. You will be facilitated with a reduction in tax liability. You need first to calculate the tax on your income and then apply the tax rebate of 33% on your total annual income.     

    (d) (exempted from the operation of any provision of this Ordinance, subject to any conditions and the extent specified therein.)

    You are tax exempt from this specific tax section as it does not apply to you. So this is how you got a tax concession.

    Subsection 2 of section 53 is specially designed for specific situations. For example, taxation in Pakistan is the homework of the National Assembly. The National Assembly of Pakistan formulates the taxes. But sometimes, the situation becomes critical, and the work has to be done in an emergency, at a very fast pace and in a strict manner. For this, requiring approval from NA becomes difficult. So that’s why a particular condition is taken into consideration. 

    The Board with the approval of the Federal Minister- in charge may, from time to time, along with the approval of the Economic Coordination Committee of the Cabinet whenever circumstances exist to take immediate action for the purposes of national security, natural disaster, national food security in emergency situations, protection of national economic interests in cases arising out of unusual fluctuation in international commodity prices, implementation of bilateral and multilateral agreements or granting an exemption from any tax imposed under this Ordinance including a reduction in the rate of tax imposed under this Ordinance or a decrease in tax liability under this Ordinance or an exemption from the operation of any provision of this Ordinance to any international financial institution or foreign Government-owned financial institution operating under an agreement, memorandum of understanding or any other arrangement with the Government of Pakistan, by notification in the Official Gazette (newspaper), make such amendment in the Second Schedule by:

    (a) addition of any clause or condition therein;

    (b) omission of any clause or condition therein; or

    (c) making of any change in any clause or condition therein,

    As the Government may think fit, all such amendments shall have effect in respect of any tax year beginning on any date before or after the commencement of the financial year in which the notification is issued.

    Subsection 3 of section 53, the Federal Government shall place all amendments made by it to the Second Schedule before the National Assembly in a financial year.

    The worth of subsection 4 has been finished. Accordingly, its time duration has ended.

    Subsection 4 of section 53, Any notification issued under subsection 2 after the commencement of the Finance Act, 2015, shall, if not earlier cancelled, remain cancelled on the expiry of the financial year in which it was issued.

    Provided that all such notifications, except those earlier cancelled, shall be deemed to have been in force with effect from the first day of July 2016 and shall continue to be in force till the thirtieth day of June 2018, if not earlier rescinded. 

    Provided further that all notifications issued on or after the first day of July 2016 and placed before the National Assembly as required under subsection (3) shall continue to remain in force till the thirtieth day of June 2018, if not earlier cancelled by the Federal Government or the National Assembly.

    Concluding Remarks:

    If the Government wants, they can make a few amendments to the second schedule. The procedure is simple. There must be approval of the federal minister, the ECC’s approval in the cabinet, and the notification to be issued in the official Gazette (newspaper). After that, any changes can be made to the second schedule.  

  • Tax Credit and Deductible Allowances:   How can you Pay Less in Taxes and Save More?

    Tax Credit and Deductible Allowances: How can you Pay Less in Taxes and Save More?

    You may have been burdened by a load of taxes or paying a heavy amount of money in taxes for a long time.

    We all have heard about the above-mentioned tax terms once. We may even get confused about their benefits, compliance, and application. Well, there is no rocket science involved in understanding these terms and using them afterward.  

    We are going to discuss these terms each after each. Then, we will illustrate them with an example to make it easy for you to get to know and understand each tax term separately.

    What is Tax Credit?

    It is a kind of tax saving; it relieves your annual income for the tax year. Thus, it helps you reduce the burden of tax on your total annual income.  

    Tax Credit is the credit given to tax, which means that when you extract all the taxes from your income and right after that when you fluctuate (increase and decrease) in the tax ratios, that is called ‘tax credit or relief.’ 

    Multiple variants of the section have been detailed in the “income tax ordinance 2001” to discuss the tax credit. From them, the essential clauses are:

    • Section 61
    • 62
    • 62A
    • 63
    • 64B
    • 64C
    • 65B
    • 65C
    • 65D
    • And 65E 

    How can you save your money by applying for a tax credit?

    You need to invest in mutual fund schemes, investment plans, or pension schemes by complying with the tax credit.

    If I invest in the organizations, do I become eligible for Tax Credits?

    Yes, if you invest in the following organizations, you would become eligible for the tax credit. Moreover, from the following sectors, you can avail yourself of tax credit benefits. And can reduce the burden of taxes.

    1. Charitable Donations (Section 61).

    If you performed a charity under section 61, you would get the tax credit; in other words, you would get the tax relief. And an important point to remember is that the particular investment must not exceed 30% of your taxable income. 

    You will get tax credits on the number of donations and donate charity in those organizations approved by the SECP. 

    You shall be entitled to a tax credit in respect of any sum you paid, or any property given by you in the tax year as a donation to:

    (a) any board of education or any university in Pakistan established by, or under, a Federal or a Provincial law;

    (b) any educational institution, hospital or relief fund established or run in Pakistan by Federal Government or a Provincial Government or a Local Government; or

    (c) any non-profit organization.

    1. Tax Credit for Investments in Shares and Insurance (Section 62).

    Suppose you invested in any company shares (listed in the PSX) and in the insurance policy so that you will get the tax credit. Suppose if you invested in shares and insurance simultaneously, you would be only entitled to a 20% tax credit on your taxable income.

    You other than your company shall be entitled to a tax credit for a tax year either:

    a) in respect of the cost of acquiring in the year new shares offered to the public by a public company listed on a stock exchange in Pakistan, provided that you are the original allottee of the shares or the shares are acquired from the Privatization Commission of Pakistan.

    b) in respect of the cost of acquiring in the tax year, sukuks offered to the public by a public company listed and traded on the stock exchange in Pakistan, provided that you are the original allottee of the sukuks; or

    c) in respect of any life insurance premium paid on a policy to a life insurance company registered by the Securities and Exchange Commission of Pakistan under the Insurance Ordinance, 2000, provided that you are deriving income chargeable to tax under the head “salary” or “income from a business.

                Credit will be given to the lesser of:

    i. the total cost of acquiring the shares, sukuks, or the total contribution or premium paid by you.

    ii. 20% of your taxable income for the year; or

    iii. two million rupees.

    The amount that could be less than among the above three mentioned amount clauses, the tax credit will be given to the lesser amount.

    1. Tax Credit for Investment in Health Insurance (Section 62A).

    The healthcare system is costly in Pakistan, and most people face problems while acquiring healthcare facilities. While keeping an eye on this, the government has put this idea under the bracket of the Income Tax Ordinance. So that people can facilitate their health insurance.  

    If you purchased the health insurance policy, then you will get the tax credit.

    You other than your company shall be entitled to a tax credit for a tax year regarding any health insurance premium or contribution paid to any insurance company, provided that you are deriving income chargeable to tax under the head “salary” or “income from the business.”

    Credit will be given to the lesser of:

    i. the total contribution or premium paid by the person

    ii. 5% of your taxable income for the year; or

    iii. one hundred and fifty thousand rupees.

    The amount that could be less than among the above three mentioned amount clauses, the tax credit will be given to the lesser amount.

    1. Contribution to an Approved Pension Fund (Section 63).

    The government provided an opportunity to the private company employees to open up a voluntary pension scheme under the income tax in their companies to secure and safely live their future.

    You are deriving income chargeable to tax under the head Salary or Income from Business. However, you shall be entitled to a tax credit for a tax year in respect of any contribution or premium paid in the year by you under a contract of annuity scheme approved by Securities and Exchange Commission of Pakistan of an insurance company duly registered under the Insurance Ordinance.

    The amount of tax examined to you for the tax year, before allowance of any tax credit under this part;

    Your taxable income for the tax year;

    Credit will be given to the lesser of:

    (i) the total contribution or premium referred to in sub-section (1) paid by you in the year; or

    (ii) 20% of your taxable income for the relevant tax year; Provided that your joining of the pension fund at the age of forty-one years or above, during the first ten years shall be allowed an additional contribution of 2% per annum for each year of an age exceeding forty years.

    (iii) Provided further that the total contribution allowed to you shall not exceed 50% of the total taxable income of the preceding year. Provided also that the additional contribution of 2% per annum for each year of an age exceeding forty years shall be allowed and subject to the condition that the total contribution allowed to such person shall not exceed 30% of the total taxable income of the preceding year.

    How to Obtain the Tax Credit Opportunity?

    To claim your tax credit amount, you need to do the following:

    1. If you are a salaried individual, you need to inform your HR or Finance Department about your investments by submitting the account statement to adjust your tax credit amount from the monthly income tax deductions.
    2. If you are a self-employed individual, you need to adjust your tax payable by showing investment in your wealth statement at the time of Income-tax return filing.

    For knowing about the remaining sections and If you want to explore further regarding the other sections, you can click on this link to educate yourself more.  

    What is Deductible Allowance?

    Deductible allowances are deducted from the gross salary so that the taxes can be applied to the net salary, and you can get some relief and bear the low burden of taxes on your salary. 

    Deductible allowances are such deductions from salary income to arrive at the taxable salary. When you calculate your salaried income, you add every sort of allowance and set the value of any benefit you get.

    Multiple variants of the section have been detailed in the “income tax ordinance 2001” to discuss the deductible allowances. From them, the essential clauses are:

    • Section 60
    • 60A
    • 60B
    • 60C
    • 60D 

    From the following sectors, you can deduct your allowances. And can reduce the burden of taxes.

    1. Zakat (Section 60):

    Not every type of Zakat can be deducted under the deductible allowances; only the typical Zakat will be deducted. And under the Zakat and Ushr Ordinance, 1980, these zakats will go into the government treasury. The majority of the Zakat, which is deducted by your bank account, national saving certificate, and other sources, Zakat will go into the Ushr Ordinance, 1980. This is how you can deduct the Zakat; it has no limit. 

    You shall be entitled to a deductible allowance for the amount of any Zakat paid by you in a tax year under the Zakat and Ushr Ordinance, 1980.

    Sub-section (1) does not apply to any Zakat taken into account under subsection (2) of section 40.

    Any allowance or part of an allowance under this section for a tax year that cannot be deducted under section 9 for the year shall not be refunded, carried forward to a subsequent tax year, or carried back to a preceding tax year. 

    1. Workers’ Welfare Fund (Section 60A):

    You shall be entitled to a deductible allowance for the amount of any Workers’ Welfare Fund paid by you in the tax year under the Workers’ Welfare Fund Ordinance, 1971.

    • Workers’ Participation Fund (Section 60B):

    You shall be entitled to a deductible allowance for the amount of any Workers’ Participation Fund paid by you in a tax year under the provisions of the Companies Profit (Workers’ Participation) Act, 1968.

    • Deductible Allowance for Profit on Debt (Section 60C):

    You shall be entitled to a deductible allowance for the amount of any profit or share in rent and share in appreciation (increase) for the value of house paid by you in a tax year on loan by a scheduled bank or non-banking finance institution regulated by the Securities and Exchange Commission of Pakistan or advanced by Government or the Local Government, Provincial Government or a statutory body or a public company listed on a registered stock exchange in Pakistan where you utilizes the loan for the construction of a new house or the acquisition of a house.

    The amount of your allowance allowed for a tax year shall not exceed 50% of taxable income or “two” million rupees, whichever is lower.

    Any allowance or part of an allowance under this section for a tax year that cannot be deducted for the year shall not be carried forward to a subsequent tax year.

    •  Deductible Allowance for Education Expenses (Section 60D):

    You shall be entitled to a deductible allowance in respect of the tuition fee paid by you in a tax year, provided that the taxable income is less than one and a half million rupees. 

    The amount of your deductible allowance allowed under sub-section (1) for a tax year shall not exceed the lesser of:

    (i) 5% of the total tuition fee paid by you referred to in sub-section (1) in the year;

    (ii) 25% of your taxable income for the year;

    (iii) an amount computed by multiplying sixty thousand with the number of your children.

    Any allowance or part of an allowance under this section for a tax year that cannot be deducted for the year shall not be carried forward to a subsequent tax year. 

    Allowance under this section shall be allowed against the tax liability of either of the parents making payment of the fee on furnishing national tax number (NTN) or name of the educational institution. 

    Allowance under this section shall not be taken into account for tax deduction computation under section 149.

    *Donations under Clause 61*

    Donations to institutions under clause 61, part I of the 2nd schedule.

    a) Amount paid as a donation to the institutions mentioned in clause 61 Part 1 of the 2nd schedule of the Income Tax Ordinance, 2001, are straightly deducted from the total income (treated like deductible allowances).

    b) The amount donated shall not exceed 30% of the taxable income in the case of you as an individual, AOP and 20% in the company’s case.

    c) The condition of payment through the banking channel is not applicable for donations to be permissible deductions.

    Concluding Remarks:

    The significant difference between a tax credit and deductible allowances is that “when you calculate all the tax ratios on your annual income, and when you increase or decrease the tax amount on that tax calculation, that is how your tax credited or you got relief from heavy tax margins.”

    Whereas “deductible allowance deducted from your overall annual income after that tax applies on the remaining amount, this is how you got taxed less.” 

    In both cases, you get benefits whether you credit the tax and deduct the deductible allowances from your annual income. 
  • Calculation of Taxes on your Salary

    Calculation of Taxes on your Salary

    Suppose you are a salaried individual and are confused by the imposition of taxes upon your income from FBR. Then you are in the right place, we will instruct you in the right direction, but we need attention on reading from your end. 

    We will discuss every aspect of your gross salary income, its categorization, and the taxes imposed upon it from FBR relating to Pakistan’s new tax slab rates. We will thoroughly guide your stance during the entire process.

    There is a rising question regarding income taxes’ slabs and calculation of taxes on income, which are very much concerning nowadays among salaried individuals. When calculating the tax on salary, you also need to look for the following attributes.

    The salary which you take to your home can be categorized into the following characteristics followed by usual tax practices and the income tax ordinance 2001:

    • Basic Salary Pay
    • House Rent Allowance
    • Conveyance Allowance or Transport Facilitation
    • Medical and Miscellaneous Allowance 

    We will illustrate it with a solid example by assuming a specific criterion followed by the attributes mentioned above of a salaried individual.

    Basic Salary Pay:

    The salary you take home after every month and around 1 – 15 days of that month is your basic pay. This salary is excluded from any extra credit and debit. As such, it is the fixed amount of money which you receive as a salary. No incentives, bonuses, commissions and overtime pay are included in it.

    Suppose your salary is Rs. 50,000/- per month, which amounts to a total of Rs. 600,000/- per year. So, you have to pay 0.3% of the tax every month, which adds up to 1.9% of the total tax on your total annual income.

    If you have a salary range of above Rs. 50,000/- per month, you have to check your tax margins through the tax calculator by clicking here on this link.

    House Rent Allowance:

    If you live in a rental house and the company gives you a rental allowance, it makes up a specific portion of your total salary, which you take to your home. Generally, the house rent allowance amounts to 40% – 50% of your basic monthly salary.

    Suppose you have a basic salary package of Rs. 50,000/- per month, so you would receive a monthly house rent allowance in the range of Rs. 20,000 – 25,000. The compliance of house rent allowance with the company can differ from company to company.

    On a lighter note, the house rent allowance is already included in your basic monthly pay. It is not given separately to any employee other than in the basic salary. There is no tax imposed separately on the rent allowance provided by the company.

    Conveyance Allowance or Transport Facilitation:

    We live in a world that has become more online-driven after the covid crisis and keeping a view on its consequences. But for regular basis employees who are getting used to travelling on public and personal transport. Companies tend to compensate them.

    For instance, you are earning Rs 50,000/- per month. So, the company will manage around 10% – 15% in your monthly salary that amounts to total money ranging from Rs. 5000 – 7500. These amounts are adjusted in your basic monthly salary and are not allotted separately. 

    On some occasions, if your company is of moderate to a higher standard. So, the company may reward you with the official office car to facilitate you with the transport convenience. You may use it for personal usage; otherwise, official usage experience is a must. All the fuel and maintenance have to be borne by the employee. 

    Medical Allowance and Miscellaneous Allowance:

    It all depends upon your job designation in your company. The medical allowance can be a part of your basic monthly salary or is provided to you separately along with other allowances and pay.

    Like other countries around the globe, the greater the job designation, the more the benefits are associated with them. And also, the nature and type of organization in particular.

    Note: Only when you possess a higher job designation in the company, so all the allowances other than the monthly salary will be allotted to you separately. And the tax is only imposed upon your salary, not on its particulars, benefits, and when it exceeds Rs. 50,000/- monthly and Rs. 600.000/- annually.

  • How to File Tax Return Online in Pakistan?

    How to File Tax Return Online in Pakistan?

    If you are looking for instruction on filing the income tax return online in Pakistan then you are at the right place Filing your tax returns online can rescue you from dozens of extra engaging activities, like paying additional charges, consulting the lawyer and agency for tax filing and lastly, looking out for the tax filing services providers. 

    Greetings from Befiler, Pakistan’s first and Online Tax Returns preparation portal. Suppose you have an active income from salary and passive income from other sources. Such as rent, profit, and bank deposits, or capital etc., then you can use Befiler to help you file your tax returns. 

    Once you sign up and enter your required information, Befiler will automatically start preparing your tax returns. After that, it will be reviewed by our tax experts, and your particulars will be submitted in the FBR Tax Filing System; that is, IRIS.

    So, why worry about the tax filing procedure when there is nothing to worry about. When you can do it yourself while using Befiler mobile app or Befiler web browser access, log in to Befiler to complete your tax returns and become a filer today.   

    Process of Filing your Tax Returns Online with Befiler Mobile App: 

    1. Sign Up on the Befiler through any medium. 
    • Select your requirement from our range of services. 
    • Gather all the required information. 
    • Enter all the required information. 
    • Reach out to our tax consultant in case you need any help.   
    • Review your entered information. 
    • Pay a minimum fee of just Rs. 2500/-. 

    How is Befiler Making a Change?

    • All the tax return filing services are provided under one roof.
    • User-friendly tax returns filing experience.
    • Facilitates with low fee, easy to use interface, secure data and transactions, and supported by tax support staff. 
    • File your tax in minutes, register your NTN, calculate your tax on salary, register your business, find your NTN and much more.     

    Filing the Tax Returns Online: A Trend in the Making. 

    Tax Awareness in Pakistan is becoming increasingly important. Therefore, the government of Pakistan is making all the necessary changes in the tax laws to promote the culture of documentation. This includes providing incentives to filers and increasing taxes for non-filers.

    To move towards an emerging economy, it is necessary for you as an individual to understand and display interest in the contribution to adopting a tax filing culture. Many people in Pakistan don’t file their tax returns because of the hefty process included.

    Let’s talk about Befiler, Pakistan’s only online tax returns preparation portal. Befiler has created an intelligent online tax return portal that has made it easy to receive NTN registration and file tax returns.  With a straightforward format of simply answering the yes and no questions. 

    Befiler has made separate divisions to submit information to make the tax preparation process easy and doable for all. So, why worry anymore about finding a tax consultant? When you have your own personal tax advisor and pocket tax assistant in your hands.   

    Avail the mobile app right now without wasting any further opportunity by clicking on this link. 

  • Filing Income Tax Returns: Late Filing is Better than Non-Filing and Notices from FBR.

    Filing Income Tax Returns: Late Filing is Better than Non-Filing and Notices from FBR.

    Income Tax Returns Filing (ITRF) is a process in which you have to disclose your income and wealth statement to the FBR. The FBR every year gives 90 days to you for filing tax returns. And the deadline gets set for every 30th September for submission of tax returns.

    The FBR asks you about your income source, and there they mention the taxes’ margin to be paid on it during the year. Your income can belong to various sources of income, including income from salary, profits, and gains from business and other professions.   

    Late filing; what if I failed to file the tax returns on time and their consequences?

    Suppose you fail to file the tax returns within the due date. In that case, the FBR, on some occasions, has to extend the tax returns filing deadline if the number of the tax filers is in large quantity, if people fail to file the tax returns due to some technicalities or if the portal and database of the FBR gets downed. 

    Suppose you did not file your tax returns within the deadline issued by FBR. So, in this condition, you need to file your extension; it can be done in two ways, either manually on RTO or online on IRIS. From both of the conditions, whether following anyone, you may get the extension.

    If you file the tax returns on the extended date, it would be perfect for you. But if somehow you failed to file the tax returns even in the extended deadline, then when the ATL will be updated on 1st March of the following year so your name won’t be included in that list. So, you would be excluded from the ATL. So, you have to pay a surcharge of Rs. 1000/- to get your name added in the ATL along with the submission of your tax returns on a timely basis. 

    When I have an opportunity, Late filing will always be better than non-filing.

    So always keep in your mind that “Late compliance is always better than non-compliance”. According to the last income tax ordinance, “the minimum penalty for late filing the tax returns is Rs. 1000/- per day”. So with every passing day, Rs. 1000/- on each day from your pocket will be charged if you don’t comply with filing the tax returns timely.

    Following the above case, if you are a salaried individual, so on non-filing and late filing related to the income tax, the minimum penalty is Rs. 10,000/-. If you fail to furnish the wealth statement so the minimum penalty would be Rs. 100,000/-. A total sum up the amount of Rs. 110,000/- will be charged to you if you delay your tax returns filing process.

    If you still haven’t filed your tax returns till now, there is nothing to worry about. Indeed, it is a late compliance, but it is way a lot better than non-compliance. We are here; if you are already a user of Befiler, then spare no time, sign in to our mobile app and provide us with your legal data so that your tax filing process would be completed as soon as possible.

    But if you are not already a user of Befiler, then the procedure is effortless to follow up. Just sign up, then sign in and provide us with your basic information. Then, you can file your tax returns from us in just Rs. 2500/- in a time period of 2-3 days. So come and file your tax returns with Befiler because, with Befiler, tax is easy.

    Issuance of notices by FBR on not filing the tax returns. What options are for me?

    Suppose you failed to file the tax returns within the due date and extended deadline. Then the FBR issues the notices to people citing the relevant income tax ordinance sections. The bureau says, “why not impose the penalty on you, because you didn’t file your tax returns in the given due date and extension deadline so now from the relevant clauses of our laws which implies on you, why not we apply it on you?”.

    Section 182 subsection one mentions “in which not filing the income tax timely for a non-salaried individual the minimum penalty is Rs. 40,000/-“. Or if you are a salaried individual, then the minimum penalty on you would be Rs. 5000/-.

    In case of non-compliance and not settling the matters of the section 182 subsection one, then the notice of section 182 subsection two would be issued right after it, “which includes the order has to be passed, and the action has to be taken”.

    Another section includes 114 subsection 4 “you have missed the tax deadline; you were required to file the tax returns, and you haven’t done it”.

    Particulars of that person required to file the income tax returns:

    • Owns a motor vehicle having engine capacity above 1000 CC
    • Owns a property exceeding 500 sq yards
    •  Salary above the taxable limit of Rs. 600,000
    • Other income above Rs. 400,000

    Section 114 Subsection 4 applies the requirements mentioned above to such people who must file their tax returns. The commissioner, concerned officer of the FBR, has the power to issue notice for filing a tax return.

    Another law, Section 114 Subsection 5, “time limitations for issuance of notice”. The commissioner can issue you the tax returns notice of the previous five years and order you to submit the tax returns of any one year and above from the last five years.

    But if you never submit any current and previous tax returns, the commissioner can issue you the notice of presenting the last ten years tax file returns or any one year and above from the last ten years.     

    There is no need to scratch your head on the notices issued to you by the FBR. Obviously, it is a law, FBR has the power to exercise it. But it has a legal defence with it. You can claim a lot of genuine excuses like there are technical issues in the tax system, you failed to obtain your bank reconciliation statement, or you could not consult with your tax advisor etc. These all the excuses are genuine.

    And there is another legal defence, that is before the imposition of FBR penalty on you, you have to establish yourself before FBR with a statement like “Your default was wilful, you intentionally delayed the procedure, and you intentionally didn’t file the tax returns. It is challenging to establish a case like this but could result in bearing the fruit in the end”. You don’t need to be scared by the notices; answer them by quickly and swiftly filing the tax returns and right away ensure your compliance.      

  • How I should Benefit from Becoming a Filer in Pakistan?

    How I should Benefit from Becoming a Filer in Pakistan?

    Whether you are a filer or a non-filer, whichsoever, however, you are bound to pay taxes but becoming a filer and being a filer has its own perks and benefits. 

    The government of Pakistan has showered the advantages, put them on the table for those who are filers, and also allotted the punishable margin (doubled the taxes) for those who are non-filers. 

    If you are a filer then you are on the safe side but if you are a non-filer then you are on the danger side. Because being a non-filer you have to bear an extra amount of money on tax charges. 

    Get to know the classification of filer and non-filer, a filer is a person who discloses the wealth details before the tax regulatory body, is the regular taxpayer, and therefore is on the active taxpayers’ list. On the other hand, a non-filer is the person who doesn’t disclose the tax details, most often doesn’t pay the taxes, and therefore is also not on the active taxpayer list consequently. 

    Now you can match and compare yourself with the above-mentioned nature of filer. Whether you are benefiting yourself or you are harming yourself from being a filer or a non-filer. 

    The current population of Pakistan is approximately 220.9 Million according to the world bank sources. An estimated less than 1% which is around (2,209,000) of people from that much total population pay taxes. According to the FBR ATL 2021 (3.12 Million), individuals and companies have registered themselves with FBR for tax filing. 

    Let’s have a look at the list of benefits to avail from, depending upon your filer status; either you are a filer or a non-filer.

    Is this how I shall be benefitted? 

    The answer is yes, but before that, a question has to be answered.  Have you done with the tax filing? If not, then do it right now. Tax filer in Pakistan is a privileged status and is considered one of the parameters of transparency and accountability. As contrasted with the non-tax filers. 

    Let’s get started with the list of benefits: 

    1. If you are a filer then you need to pay half the amount of the withholding tax, but if you are a non-filer so you have to pay in full.  
    1. If you are a filer and require to withdraw cash of more than Rs 50,000 then you need to pay only 0.3% tax, but if you are a non-filer so you have to pay 0.6% tax. 
    1. If you are a filer then you need to pay 15% tax on dividends (the company’s profit), but if you are a non-filer so you have to pay 20% tax.  
    1. If you are a filer then you need to pay 10% tax on profits of banks and saving schemes, but if you are a non-filer so you have to pay 15% tax. 
    1. If you are a filer then you need to pay 15% tax on winning the prize bond amount, but if you are a non-filer so you have to pay 25% tax. 
    1. If you are a filer then you need to pay 12% tax on the commission amount, but if you are a non-filer so you have to pay 15% tax. 
    1. If you are a filer then you need to pay 10% tax on any auction from the government and private party, but if you are a non-filer so you have to pay 15% tax. 
    1. If you are a filer who regularly files the taxes then you are allowed to purchase any property, but if you are a non-filer so you are restricted to owning a property that is worth Rs. 5 Million and above.  
    1. If you are a filer then you need to pay 2% tax on the total amount of the property purchased, but if you are a non-filer so you have to pay 4% tax. 
    1. If you are a filer then you need to pay 1% tax on the transfer of property, but if you are a non-filer so you have to pay 2% on the transfer of property. 
    1. If you are a filer then you need to pay 5.5% duty on the raw material imports, but if you are a non-filer so you have to pay 8% duty on raw material imports. 
    1. If you are a filer then you need to pay 6% duty on your commercial exports, but if you are a non-filer so you have to pay 9% duty. 
    1. If you are a filer then you need to pay 4.5% duty on the supply of goods to the government and companies, but if you are a non-filer so you have to pay 9% duty. 
    1. If you are a filer then you need to pay 7.5% tax on the contracting amount, but if you are a non-filer so you have to pay 15% tax. 

    Mentioned below is a comparison list between filers and non-filers. In the contexts of bank funds transfer, vehicle ownership, registration, and transference.

    Difference in applicable taxes for filer and non-filers

    If you don’t already become a tax filer, then what are you waiting for? Befiler is here for you, to make you a tax filer without any inconvenience and with all ease. Just don’t wait anymore and click on the link because with Befiler becoming a tax filer is just a click away.  

  • Strategy for FBR Transformation and Enhancement of Tax Collections

    Strategy for FBR Transformation and Enhancement of Tax Collections

    Millions of Pakistani rupees have been spent so far on the restructuring of the FBR board and ‘reforming’ the tax administration over the last two decades or so. 

    But without the growth factor, the tax system and collection can’t be nourished and flourished. The harassment in the tax collection systems to the taxpayers must be brought down and should be avoided as much as possible. 

    Tax incentives should be given to industries, businesses, and entrepreneurs. The encouragement of these very industries is the need of the hour. Unless they are reinforced and empowered with relief packages, nothing is going to work for both of them.  

    It would be unfair to lay the entire blame on the tax collectors alone, everybody in the system is equally responsible. 

    Following are some strategic points that can relate to the articulation of policies for FBR.  

    1. Constitution of the FBR board and governance system, restructuring of the FBR within and also to involve people externally, in a sum up a combination of intellectual, capable, and determinant people have to be placed.  
    1. Policy initiatives have to be taken, a national tax policy has to be formulated and constituted. Hence, there are three different provincial tax collection bodies which include: excise and taxation department, board of revenue, and revenue board. Lastly, the federal tax collection bureau FBR, which is the central tax collection body. All of these bodies are operating separately but have the same objective. So, therefore, a uniform tax collection and regulation authority has to be formed, branded, and organized, as “National Tax Agency”. 
    1. FBR has to set up a uniform data organization in terms of data analytics, data collection, and data integration. While doing this, FBR has to incorporate people from the private sector. There should be an organizational data-driven strategy that must be inclusive of data; collection, integration, analysis, automation, reprocessing, and simplification of tax laws. 
    1. Performance management and accountability of the outcome is inevitable and second to none because this will pave the way for future endeavors and open the doors for the future course of actions. 

    Concluding remarks: 

    FBR has to collect the tax in such a systematic way that it neither force and nor coerce it. They should collect the tax likewise so that people don’t feel pain, the economy does not get hurt, and but simultaneously weighing both components; tax gets collected and its volume gets increased. This is what the fundamentalism of taxes is. 

  • Pakistan’s Tax Culture

    Pakistan’s Tax Culture

    A tax culture in its ordinary definition shows us the existing tax activities and tax principles of a specific country. Both the actions and reactions of taxpayers and tax collectors are the foundational basis of the tax culture. 

    In Pakistan tax culture, taxes are categorized into two main categories: 

    1. Direct tax. 
    2. Indirect Tax. 

    Direct tax is simply the tax on your income. On the other hand, indirect tax is sale tax, service tax, customs duty, and excise duty. 

    The Government of Pakistan equipped the Federal Board of Revenue (FBR) to impose and collect the taxes. The motive of FBR is to expand the tax net and to broaden the tax collection capacity while using certain tax collection techniques, assistance to taxpayers, and empowering the dedicated workforce.        

    According to FBR, only 1% of the total 220+ Million population of Pakistan pay taxes. If compared to India around 4% of the total 1.38 Billion population pays taxes. Pakistan’s tax-to-GDP ratio is equal to 10.2% taxes of the $263.7bn GDP according to the 2021FY.  Pakistan ranks at 161st position internationally in terms of taxpayers ratio. 

    Following these consequences of tax affairs, the fiscal deficit has become a prolonged macroeconomic issue of Pakistan’s economy. Pakistan’s fiscal deficit stands at 7.1% (3.403 trillion) of GDP in the year 2020-2021. Fortunately, this is the lowest fiscal deficit ratio in the last three financial years. 

    People avoid, escape, and hesitate to pay taxes because of multiple reasons, few of them are: 

    1. Lack of tax awareness. 
    1. Dishonest public regime. 
    1. Corruption in departments. 
    1. Exploitation of taxpayers. 
    1. Complicated tax procedures and regulations. 
    1. Heavy tax reliance on income and sale. 

    According to the survey report of FBR 2019, FBR identified various factors which lead to demotivation and discouragement in the general public referring to paying taxes, these factors includes: 

    1. 51% of the people do not pay taxes because of the corruption in the governance system. 
    1. 20% of the people do not pay taxes because of their belief in the misuse and exploitation of tax money. 
    1. 18% of the people do not pay taxes because they have low income and are left with less disposable income. 
    1. 9% of the people do not pay taxes because of faults in the tax collection mechanism.   
    1. 2% of the people do not pay taxes because they find taxes and tax filing as a burden.  

    Our society’s dilemma is that the general public perceives the certain amount which is collected through taxes is looted by the regime rulers and then spent on the luxury lifestyle of the powerful and elite class in Pakistan. 

    Frequently, the government of Pakistan spends the taxpayers’ money on non-productive projects such as building roads, flyovers, and insufficient public transport. If the elite class intends to pay the taxes and the government ensures the appropriate utilization of the taxes then an estimated 90% of the eligible people would be following to pay the taxes.     

    The government must develop a comprehensive tax system, in which it should incorporate all the tax mechanisms, tax norms should be compatible with our tax culture, and in order to nourish and flourish the tax culture, the government must emphasize on prevailing the tax mentality in the society.

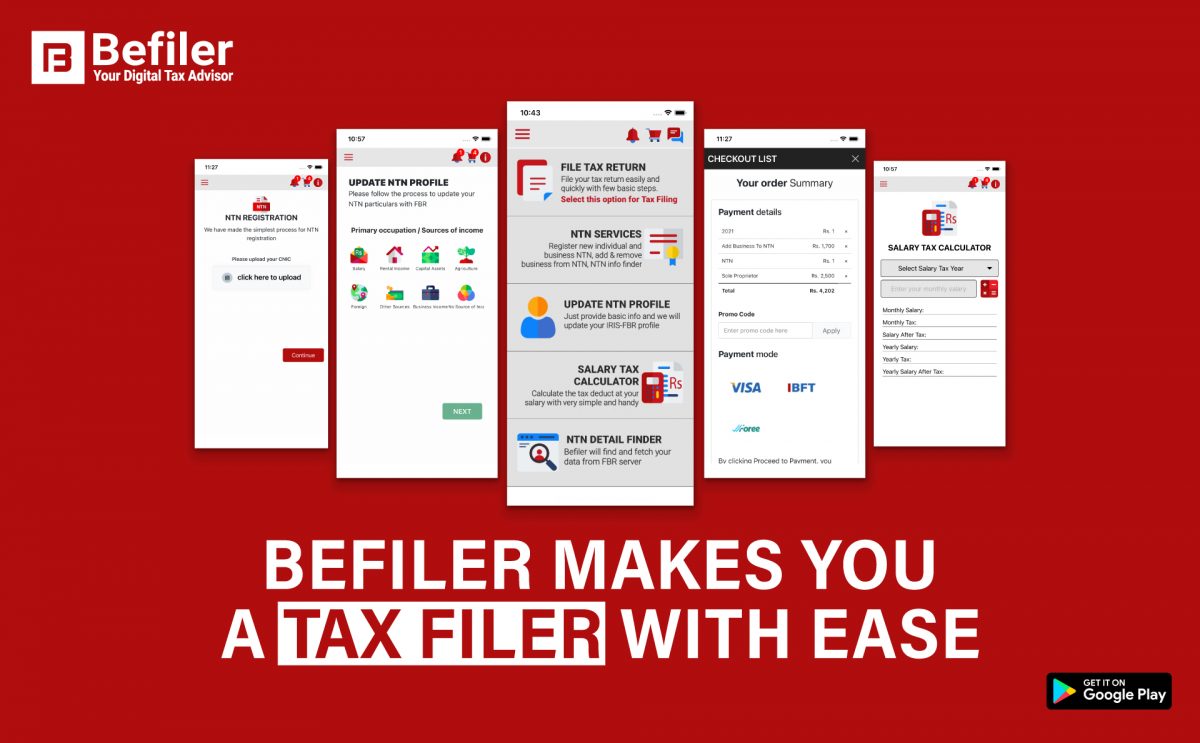
  • Befiler Makes You a Tax Filer with Ease

    Befiler Makes You a Tax Filer with Ease

    Befiler is a website and mobile-based tax filing portal, which allows you to file your tax returns digitally. Not only just filing the tax returns, you can register your National Tax Number (NTN), business, and can calculate the tax. 

    Whether you are a doctor, engineer, businessman, freelancer, or any other profession in the queue. With Befiler you can file the tax returns and by doing so you fulfilled the national obligation and played your pivotal part in the nation building structure of our beloved country Pakistan.     

    Who is filer?

    The Pakistani Government breaks down its definition of filer in the tax field into two categories:

    Filer

    If you are a filer, then you are not only paying the taxes but also documenting them with FBR by declaring all the necessary information. 

    Non-filer. 

    If you are a non-filer, then your taxes are already being deducted at a higher rate and additional benefits are held as compared to tax filers, for example you pay extra taxes on purchasing of automobiles, property and so on.

    Benefits of becoming a tax filer in Pakistan? 

    Following are the ways by which you would be benefited by becoming a filer in Pakistan:

    • Being a tax filer in Pakistan, you will be charged less on the profits earned and on the cash withdrawals. 
    • You will have to pay less withholding tax (such as the tax which you have already paid on the income earned and gain on benefits). 
    • When you become a tax filer, you will have to pay less charges on vehicle registration and vehicle ownership transference. 
    • You will have to pay a lower rate of tax on the buying and selling of your properties.

    Why should I file my tax returns with Befiler?

    We know our why, and can answer your how, so we have listed a few distinguished cutting-edge benefits of choosing Befiler.   

    • Pakistan’s only online tax filing portal, where all your tax filing-oriented requirements are catered and served in one go.   
    • An easy tax filing solution, with attractive, eye-catching user interface and user experience; which won’t let you skip the app and roam on to other apps. 
    • Qualified and Professional tax team is on the backup support, composed of experienced lawyers and tax consultants, which can facilitate you on live call and text support.     
    • Befiler charges a nominal fee of Rs. 2650/- for income tax filing. We guarantee and assure your information, data security and keep it confidential between us by not sharing it with 3rd parties. 
    • Befiler saves your valuable time and effort by opting for the digital tax filer, instead of traditional tax filers who charge you extra and await your process for days.